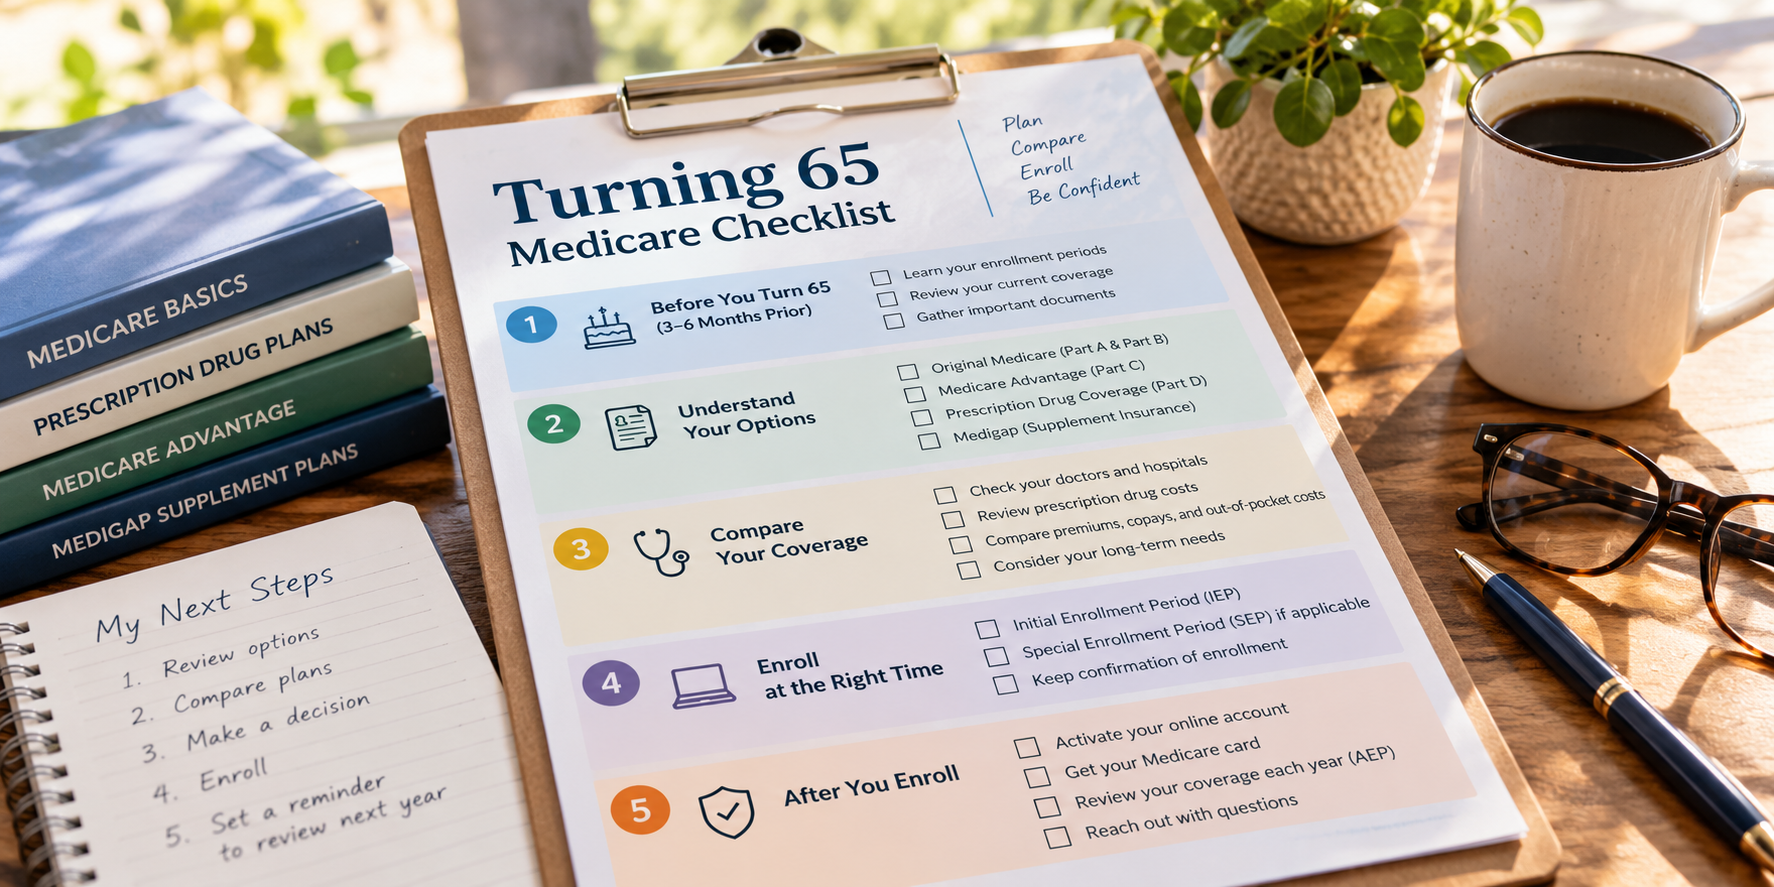
For most Americans, turning 65 brings an important change in how they pay for healthcare. After decades of relying on insurance through an employer, a spouse, or the individual marketplace, Medicare becomes available as a new source of coverage. Yet Medicare does not always begin automatically, and the date someone celebrates their 65th birthday is not necessarily the deadline for enrolling. Instead, the federal government provides a specific window of time to sign up, with rules that can affect when coverage begins and whether additional costs apply. Understanding the Medicare Initial Enrollment Period is essential because enrolling at the right time can prevent gaps in healthcare coverage, avoid unnecessary penalties, and preserve important choices about insurance during retirement. The process begins with knowing when the enrollment window opens, but making a sound decision also requires understanding how Medicare works with existing insurance and what happens after enrollment.
For someone approaching retirement, these decisions may arrive alongside several other financial changes. An employer may be preparing to end health benefits, a spouse may still be working, or a retiree may be considering whether to purchase supplemental insurance. Each circumstance can influence the appropriate time to enroll. Although the Initial Enrollment Period follows a standard federal schedule, the best course of action is not identical for everyone. Understanding the difference between Medicare eligibility, enrollment, and the start of coverage helps make the transition more predictable.
The Seven-Month Window That Begins Before Your 65th Birthday
The Medicare Initial Enrollment Period, often called the IEP, is generally a seven-month period surrounding a person's 65th birthday. It begins three months before the month someone turns 65, includes their birthday month, and continues for three months afterward. This is the first opportunity for most people becoming eligible at 65 to enroll in Medicare Part A, which provides hospital insurance, and Part B, which covers physician services, outpatient treatment, and many preventive services. The seven-month period provides time to make arrangements before existing coverage ends.
Consider someone whose 65th birthday falls on June 15, 2027. Their Initial Enrollment Period begins March 1 and ends September 30. Although the birthday occurs in June, they can submit their Medicare application in March, April, or May to arrange for coverage to begin June 1. Someone who waits until June or later can still enroll during the seven-month window, but their coverage will generally begin on the first day of the month following enrollment. This difference can matter when employer insurance ends at the beginning of retirement.
There is an important exception for people born on the first day of a month. Medicare treats their eligibility differently, moving the enrollment window and normal coverage start date one month earlier. For example, someone born on June 1 would generally have an Initial Enrollment Period running from February through August, with Medicare coverage potentially beginning May 1. This rule may seem minor, but overlooking it can affect coordination with existing insurance. Checking the actual enrollment dates rather than relying only on the birthday month helps prevent avoidable mistakes.
Enrolling during the first three months of the Initial Enrollment Period is generally the simplest approach for someone who wants Medicare to begin as soon as they become eligible. It provides time to complete the application, receive confirmation, and consider additional coverage. People who enroll later in their window are not automatically penalized simply for waiting, but the later effective date can create problems if their previous insurance has already ended. For that reason, planning several months before turning 65 is usually more practical than treating the birthday itself as the starting point.
Enroll March–May
Coverage can generally begin June 1.
Enroll June–September
Coverage generally begins the first day of the following month.
Illustrates the standard age-65 enrollment scenario described above. A birthday on the first of the month generally moves the enrollment window and normal coverage start one month earlier. Individual enrollment circumstances may differ.
Why Some People Are Enrolled Automatically While Others Must Apply
Not everyone approaching 65 needs to submit a Medicare application. People already receiving retirement benefits from Social Security or the Railroad Retirement Board are generally enrolled automatically in Medicare Part A and Part B when they become eligible. Their Medicare card is typically mailed about three months before their 65th birthday, giving them an opportunity to review the effective dates and decide whether they need to take further action. Certain exceptions apply, including different Part B enrollment rules for people living in Puerto Rico.
However, many Americans now continue working or delay collecting Social Security retirement benefits beyond age 65. Someone in this situation generally must actively apply for Medicare rather than waiting for a card to arrive. Applications for Part A and Part B are handled through the Social Security Administration, not through a private insurance company. Individuals can begin the process online at SSA.gov or contact Social Security for assistance. Those who worked for a railroad may need to coordinate with the Railroad Retirement Board instead.
The distinction between automatic enrollment and applying independently is especially important for people who assume Medicare will begin simply because they have reached the eligible age. A person who is not receiving Social Security benefits could turn 65 without having Medicare coverage in place. If their employer insurance ends around the same time, that misunderstanding may leave them without the protection they expected. Confirming whether enrollment will happen automatically should therefore be one of the first steps in preparing for Medicare.
People who receive automatic enrollment should also review their Part B coverage carefully before declining it. Part B generally requires a monthly premium, and someone with qualifying employer coverage may have a reason to delay enrollment. Nevertheless, declining Part B without understanding the applicable rules can create future enrollment difficulties or penalties. The decision should be based on the type of insurance a person currently has, not simply on whether they would prefer to avoid another monthly expense.
When Employer Health Insurance Changes the Enrollment Decision
For Americans who continue working after 65, the Initial Enrollment Period introduces a different question: whether Medicare should replace existing coverage or work alongside it. Some people can delay Part B enrollment without a late penalty because they have group health insurance through their own current employment or their spouse's current employment. Others may need Medicare at 65 even though they remain employed. The distinction depends on the employer's coverage arrangements, the size of the employer, and which insurance is responsible for paying medical claims first.
Employer size is particularly important. For most people eligible for Medicare because of age, group health coverage from an employer with 20 or more employees generally pays before Medicare. In this situation, someone may be able to postpone Part B while maintaining qualifying coverage through current employment. When the employer has fewer than 20 employees, Medicare generally pays first, which means delaying Part B could leave substantial expenses unpaid. Certain exceptions apply, so the employer's benefits administrator should confirm how the coverage coordinates with Medicare.
A person who qualifies to delay Part B because of current employment may later use a Special Enrollment Period. Under the rules described in Medicare & You 2027, this opportunity generally remains available while qualifying employer group coverage continues and for eight months after the employment or coverage ends, whichever happens first. Enrolling during the appropriate Special Enrollment Period generally avoids the Part B late enrollment penalty. This protection allows many people to continue working without being forced to enroll in Part B solely because they have turned 65.
However, not every form of health insurance provides this protection. COBRA continuation coverage, retiree health insurance, Veterans Affairs coverage, and individual marketplace policies are not treated as group coverage based on current employment for this purpose. Someone relying on these arrangements could face a penalty or delay by assuming they can postpone Medicare enrollment indefinitely. People with Health Savings Accounts must also consider the tax consequences of Medicare enrollment, since contributions generally cannot continue once Medicare coverage begins. These details make it important to examine existing coverage before deciding whether to enroll or delay.
What Happens If You Miss Your Initial Enrollment Period?
Missing the Initial Enrollment Period does not necessarily mean losing access to Medicare permanently, but it can make the process more expensive and less convenient. Someone who fails to enroll in Part B when first eligible and does not qualify for a Special Enrollment Period may need to wait for the General Enrollment Period. This enrollment window runs from January 1 through March 31 each year. Coverage generally begins on the first day of the month after enrollment, which may leave a person waiting longer than expected for Medicare benefits.
The financial consequences can last much longer than the initial delay. Medicare generally increases the Part B premium by 10% for each full 12-month period someone could have enrolled but did not, unless an exception applies. The penalty is typically added to the monthly premium for as long as the person maintains Part B coverage. Someone who delays enrollment for several years without qualifying coverage may therefore pay more for Medicare throughout retirement. People who must purchase Part A can also face separate late enrollment penalties under applicable rules.
For example, a person who delays Part B for two full years without qualifying for a Special Enrollment Period could generally face a 20% Part B late enrollment penalty. This is an illustration of the penalty formula, not a calculation of a particular person's premium. Because the surcharge is tied to the applicable Part B premium, the dollar amount may change as premiums change. The more important lesson is that failing to enroll at the correct time can create an ongoing expense rather than a one-time administrative inconvenience.
Medicare does recognize that some people miss enrollment because of circumstances outside their control. Certain emergencies, natural disasters, loss of Medicaid, and errors involving an employer or health plan may qualify someone for an exceptional Special Enrollment Period. These protections are subject to specific requirements and should not be assumed to apply automatically. Anyone who has missed their enrollment window should investigate available options rather than conclude that a penalty is unavoidable.
Enrolling in Medicare Is Only the Beginning of Choosing Coverage
Once Part A and Part B enrollment is arranged, beneficiaries must decide how they want to receive their Medicare benefits. Original Medicare provides hospital and medical coverage directly through the federal program and generally allows patients to visit any participating Medicare provider nationwide. Beneficiaries can also purchase separate Part D prescription drug coverage and may choose Medicare Supplement insurance, commonly called Medigap, to help pay certain expenses that Original Medicare leaves behind.
Medicare Advantage offers another approach. These plans are administered by private insurance companies approved by Medicare and provide an alternative way to receive Part A and Part B benefits. Most include prescription drug coverage, and many offer additional benefits such as routine dental, vision, or hearing services. However, Medicare Advantage plans may use provider networks, require referrals or prior authorization, and charge different copayments or coinsurance amounts. Neither approach is universally better, and the appropriate choice depends on healthcare needs, finances, preferred providers, and personal priorities.
The Initial Enrollment Period is particularly important because it also provides an opportunity to establish coverage arrangements that may be harder to obtain later. Federal Medigap rules generally provide a six-month open enrollment period beginning when a person is at least 65 and enrolled in Part B. During that protected period, insurers generally cannot deny a Medigap policy or charge more because of health conditions. Outside the protected window, medical underwriting may apply in many states, although federal guaranteed-issue rights and additional state protections can create exceptions.
Prescription drug coverage also requires attention. Someone who chooses Original Medicare generally needs a separate Part D plan if they want Medicare prescription coverage, while most Medicare Advantage plans include it. Going without Part D or other creditable prescription drug coverage for too long can result in a separate late enrollment penalty. A person who enrolls in Parts A and B on time has therefore completed an important step, but not necessarily the entire process of arranging suitable healthcare coverage.
Conclusion: A Well-Timed Decision Can Make Retirement More Secure
The Medicare Initial Enrollment Period is more than a seven-month administrative deadline. It is the first major opportunity for most Americans turning 65 to establish healthcare coverage that fits their retirement plans. Enrolling during the appropriate window can help prevent gaps in medical protection, avoid unnecessary premium penalties, and provide time to compare coverage options. Just as importantly, understanding when enrollment may be delayed because of qualifying employer insurance can prevent someone from making a decision that creates unnecessary costs.
The most effective approach begins several months before the 65th birthday. Confirm whether Medicare enrollment will happen automatically, review existing health insurance, and determine when Part A and Part B should begin. From there, consider how prescription drug coverage, Medicare Advantage, or Medigap may fit into the overall plan. These decisions are connected, and treating them as parts of one process makes it easier to understand both their immediate and long-term consequences.
At Beacon Senior Health Advisors, we help individuals approaching Medicare eligibility understand their enrollment timelines and compare the coverage options available to them. Our goal is to make the transition easier to understand so that decisions are based on accurate information rather than uncertainty or pressure. Turning 65 may open the door to Medicare, but knowing when and how to walk through it can make a meaningful difference in the years that follow.
References and Further Reading
Centers for Medicare & Medicaid Services. Medicare & You 2027. Official U.S. Government Medicare Handbook, Publication No. 10050. Relevant sections include pages 15–18, covering automatic enrollment, the Initial Enrollment Period, Special Enrollment Periods, and the General Enrollment Period; pages 19–21, covering other health insurance and employer coverage; pages 22–23, covering premiums and late enrollment penalties; pages 79–82, covering Medigap; and pages 83–89, covering prescription drug enrollment and costs.
Social Security Administration. Sign Up for Medicare.
Medicare.gov. When Does Medicare Coverage Start?.
Medicare.gov. Special Enrollment Periods.
Educational disclaimer: This article provides general information about Medicare enrollment and coverage. Individual eligibility, enrollment rights, premiums, penalties, and coordination with other insurance may vary. Readers should confirm their circumstances with Medicare, Social Security, or a qualified insurance professional before making enrollment decisions.
Written by Malachi Ulysse
Founder & Advisor, Beacon Senior Health Advisors
Licensed Insurance Broker Since 2019