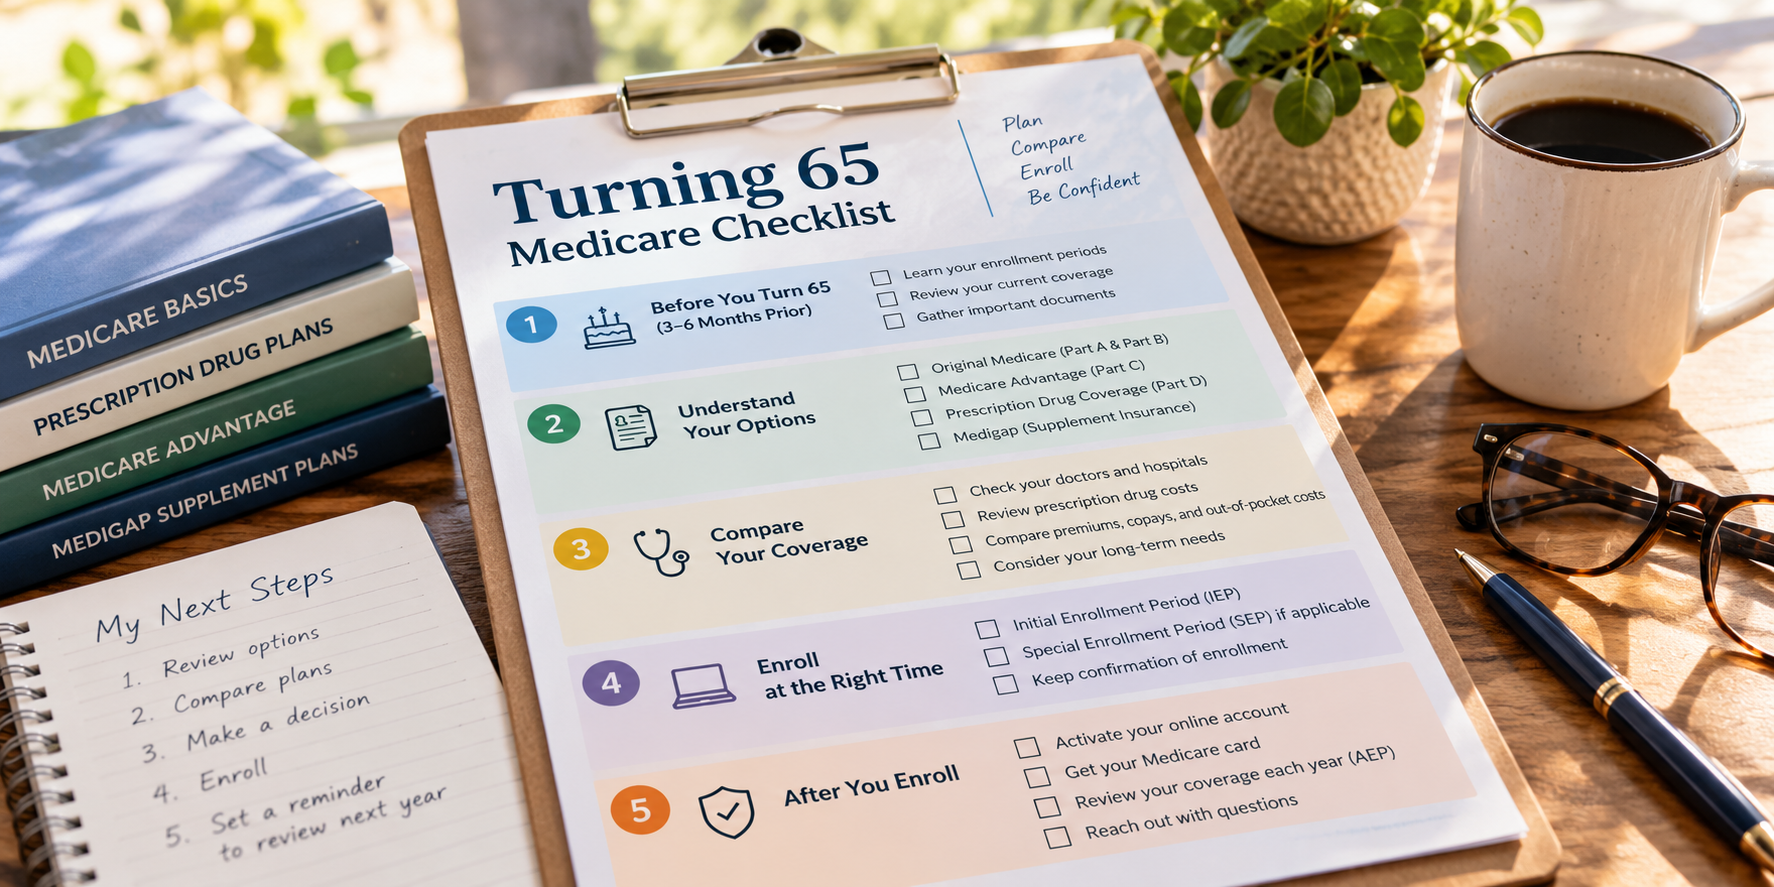
Imagine reaching retirement only to discover that your health insurance is about to end and Medicare will not begin when you expected. Perhaps you assumed enrollment was automatic, believed your old employer coverage would protect you, or simply lost track of the deadline while managing everything else that comes with turning 65. Now, instead of enjoying the freedom of retirement, you are wondering whether your next doctor's appointment will be covered and how much the mistake might cost. Missing a Medicare enrollment deadline can lead to delayed coverage, higher monthly premiums, and fewer insurance choices, but the consequences depend on which deadline you missed and whether you qualify for an exception. The most important thing to understand is that missing a Medicare deadline does not mean losing Medicare forever. It means knowing which enrollment rules apply, what financial risks you face, and how to restore coverage as quickly as possible.
Medicare has several enrollment periods, each serving a different purpose. The first determines when most people can enroll in hospital and medical insurance around age 65. Others allow people to enroll after leaving employer coverage, purchase prescription drug insurance, or change their Medicare health plans. Confusing these deadlines can be costly because the rules for correcting a missed enrollment opportunity are not always the same. Understanding those differences is the first step toward making an informed decision rather than allowing one missed date to become a lasting financial problem.
The First Deadline: Enrolling in Medicare at Age 65
For most Americans, the first major Medicare deadline arrives around their 65th birthday. The Initial Enrollment Period lasts seven months, beginning three months before the birthday month, including that month, and ending three months afterward. Someone who turns 65 on June 15, for example, generally has from March 1 through September 30 to enroll in Medicare Part A and Part B. Part A helps cover inpatient hospital care, while Part B covers physician services, outpatient treatment, and many preventive services. People born on the first day of a month have an enrollment period that begins and ends one month earlier.
Some people never have to worry about submitting that first application because enrollment happens automatically. Individuals already receiving Social Security or Railroad Retirement Board benefits are generally enrolled in Part A and Part B when they become eligible at 65, subject to certain exceptions. However, people who have delayed claiming retirement benefits usually must apply themselves. This distinction can catch working Americans by surprise, particularly those who assume that reaching age 65 automatically activates Medicare. Receiving a birthday card from Social Security is not the same as receiving a Medicare card with confirmed coverage dates.
If someone misses the Initial Enrollment Period, the consequences depend largely on whether they had another type of qualifying insurance. A person who continued working and maintained employer group coverage may have the right to enroll later without a penalty. Someone who relied on an individual health insurance policy, retiree benefits, or COBRA continuation coverage may not have that same protection. Before assuming a deadline has been missed, it is therefore important to determine whether the person was required to enroll in the first place. Medicare rules recognize certain situations in which delaying enrollment is entirely appropriate.
When Missing the Deadline Means Waiting for Coverage
For someone who missed the Initial Enrollment Period and does not qualify for a Special Enrollment Period, the next opportunity to enroll in Part B is generally the Medicare General Enrollment Period. This runs from January 1 through March 31 each year. Under the rules described in Medicare & You 2027, coverage begins on the first day of the month after enrollment. Although this provides a way to enter Medicare after missing the original deadline, it may also create a period during which someone has no Part B coverage.
Consider a hypothetical retiree who turned 65 in April but did not enroll in Part B during the seven-month window. By November, the retiree discovers that their individual health insurance does not provide a Medicare Special Enrollment Period. Unless another exception applies, they may need to wait until January to enroll, with coverage beginning in February. During the intervening months, medical appointments, diagnostic tests, and outpatient treatment could create expenses that would otherwise have been covered in part by Medicare. The exact financial impact would depend on any other insurance available during that time.
The delay can be especially difficult for people managing ongoing health conditions. Someone who needs regular specialist appointments or outpatient treatment may find that waiting even a few months creates both financial and practical concerns. Providers may require payment arrangements, and a person may need to determine whether existing insurance remains valid after Medicare eligibility begins. Because the General Enrollment Period does not automatically erase the consequences of a missed deadline, restoring coverage should be treated as a priority rather than postponed until the next medical need arises.
The Financial Consequences of Enrolling Late
One of the most significant consequences of missing the Medicare enrollment deadline is the possibility of a permanent increase in monthly premiums. Medicare Part B generally imposes a late enrollment penalty equal to 10% of the standard Part B premium for each full 12-month period a person could have enrolled but did not, unless an exception applies. Unlike a late fee that disappears after payment, this surcharge generally continues for as long as the person has Part B. Over many years of retirement, even a relatively modest monthly increase can add up.
For example, imagine someone who delays Part B enrollment for two full years without qualifying employer coverage or another exception. That person could generally face a 20% premium penalty. If the applicable standard Part B premium were hypothetically $200 per month, the surcharge would be $40 monthly, or $480 annually. This is an illustration of how the penalty works, not an actual 2027 premium quotation. The real dollar amount depends on the applicable premium, and the penalty can change as that premium changes.
Medicare Part A has a different penalty structure. Most people qualify for premium-free Part A because they or a spouse paid Medicare taxes for a sufficient period. Those who must purchase Part A and fail to enroll when required may face a premium increase of 10%. Generally, the higher premium applies for twice the number of years they delayed enrollment. Although fewer beneficiaries face this particular penalty, it remains important for people who do not qualify for premium-free hospital insurance.
Prescription drug coverage presents another financial risk. Medicare Part D has its own late enrollment penalty, which can apply when someone goes 63 consecutive days or more after their Initial Enrollment Period without Part D or other creditable prescription drug coverage. Creditable coverage means prescription insurance expected to pay, on average, at least as much as standard Medicare drug coverage. The Part D penalty is generally calculated as 1% of the national base beneficiary premium for each full uncovered month and is usually added to the person's monthly drug plan premium for as long as they have Part D. Certain exceptions apply, including for people receiving Extra Help.
These penalties reveal an important feature of Medicare: different parts of the program have different enrollment rules. Enrolling in Part A does not necessarily protect someone from a Part B penalty, and having Part B does not eliminate the need to consider prescription drug coverage. A person who misses more than one deadline may face separate consequences. Understanding exactly which part of Medicare was delayed is therefore essential before calculating potential costs or deciding what to do next.
When Missing a Deadline Does Not Mean Paying a Penalty
Fortunately, Medicare recognizes that many people continue working beyond age 65. Those who have group health coverage through their own current employment or a spouse's current employment may qualify for a Special Enrollment Period to enroll in Part B later. This opportunity generally remains available while qualifying employer coverage continues and for eight months after the employment or coverage ends, whichever happens first. People who enroll during the appropriate period usually avoid the Part B late enrollment penalty, even if they are several years past their 65th birthday.
The type of employer coverage matters, however. For people eligible for Medicare because of age, insurance through an employer with 20 or more employees generally pays before Medicare, while Medicare usually pays first when the employer has fewer than 20 employees. Someone working for a smaller employer may therefore need Part B at 65 to avoid unpaid medical expenses, even if they remain on the company's health plan. Confirming the employer's size and payment rules is an important part of deciding whether delayed enrollment is appropriate.
Medicare also provides Special Enrollment Periods for certain unusual circumstances. According to the 2027 handbook, these may include natural disasters, emergencies, employer or health plan errors, incarceration, and the loss of Medicaid coverage. Eligibility depends on the circumstances and the applicable requirements, so an exception should never be assumed without verification. People who believe their missed deadline resulted from one of these situations should contact Social Security or Medicare promptly and ask whether a Special Enrollment Period is available.
How a Missed Deadline Can Affect Your Coverage Choices
The consequences of missing a deadline extend beyond enrolling in Parts A and B. For someone considering Medicare Supplement insurance, commonly called Medigap, the timing of Part B enrollment can affect important consumer protections. Federal law generally provides a six-month Medigap Open Enrollment Period beginning when a person is at least 65 and enrolled in Part B. During this period, insurance companies generally cannot deny a Medigap policy or charge more because of a person's health conditions. Outside that window, medical underwriting may apply unless another federal or state protection is available.
This distinction can become important when someone tries to change coverage later in retirement. A person who originally selected Medicare Advantage may decide that Original Medicare with Medigap better suits their needs. Although Medicare provides certain opportunities to leave Medicare Advantage, that does not always guarantee the right to purchase a Medigap policy without health questions. State protections and certain trial rights may help, but they vary by situation. Missing an enrollment opportunity can therefore affect not only when coverage begins, but also which insurance arrangements remain available.
It is also important to distinguish missing the first Medicare enrollment deadline from missing the annual Medicare Open Enrollment Period. The annual period runs from October 15 through December 7 and allows eligible beneficiaries to make changes to Medicare Advantage and Part D coverage for the following year. Missing that window generally means keeping existing coverage unless another enrollment opportunity applies. People already enrolled in Medicare Advantage also have a separate period from January 1 through March 31 to make certain changes. These deadlines serve different purposes and should not be confused with the Initial Enrollment Period at age 65.
1. Confirm your status
Check whether Parts A and B are active and confirm the effective dates.
2. Review prior insurance
Identify the coverage you maintained and whether it was based on current employment.
3. Ask about an enrollment period
Contact Social Security or Medicare about a Special Enrollment Period or the next available window.
4. Review the remaining pieces
Check prescription coverage, possible penalties, and Medigap enrollment protections.
Individual rules and exceptions vary. Confirm your eligibility and coverage start date before ending other insurance.
Conclusion: One Missed Deadline Does Not Have to Define Your Retirement
Missing a Medicare enrollment deadline can create real financial consequences, particularly when it results in delayed Part B coverage or premiums that remain higher for years. Yet the outcome is not always as severe as people initially fear. Some individuals qualify for Special Enrollment Periods, others may still be within their original enrollment window, and certain circumstances can provide relief from penalties. The key is determining which rules apply before assuming that the next step must involve waiting or paying more.
Anyone who believes they have missed a deadline should first confirm their current Medicare enrollment status and the type of insurance they have maintained. From there, they can determine whether a Special Enrollment Period applies, when coverage could begin, and whether a late enrollment penalty is likely. It is equally important to review prescription drug coverage and supplemental insurance choices so that correcting one problem does not leave another unresolved. A careful review can turn an uncertain situation into a practical plan.
At Beacon Senior Health Advisors, we help people understand Medicare enrollment rules and how they apply to their individual circumstances. If you have missed a deadline, are approaching retirement, or are uncertain whether your current insurance allows you to delay Medicare, speaking with a licensed advisor can help you understand your options. Schedule a consultation with Beacon Senior Health Advisors at www.beaconseniorhealth.com to discuss your situation. A missed date may complicate the road ahead, but understanding your choices can help you move forward with greater confidence.
References and Further Reading
Centers for Medicare & Medicaid Services. Medicare & You 2027, Publication No. 10050. Pages 15–18 discuss Medicare enrollment periods, Special Enrollment Periods, and the General Enrollment Period. Pages 22–23 explain Part A and Part B late enrollment penalties. Pages 75–76 address Medicare Advantage enrollment changes, pages 79–82 discuss Medigap, and pages 83–89 address Medicare prescription drug enrollment and penalties.
Social Security Administration. Sign Up for Medicare.
Medicare.gov. When Can I Sign Up for Medicare?.
Medicare.gov. Medigap Enrollment.
Educational disclaimer: This article provides general information about Medicare enrollment and coverage. Eligibility, enrollment rights, premiums, penalties, and insurance availability depend on individual circumstances and applicable federal or state rules. Confirm your specific situation with Medicare, Social Security, or a qualified insurance professional before making coverage decisions.
Written by Malachi Ulysse
Founder & Advisor, Beacon Senior Health Advisors
Licensed Insurance Broker Since 2019